Lease Calculator
Estimate an auto lease monthly payment using vehicle price, down payment, residual value, term, interest rate, tax, and upfront fees.
Lease Results
This calculator provides an estimate only. Actual lease payments can differ because of dealer fees, acquisition fees, registration costs, taxes, incentives, credit tier, mileage allowance, security deposit, disposition fee, and whether fees are paid upfront or rolled into the lease.
The Lease Calculator estimates the monthly and total cost of using a vehicle for a defined term and mileage allowance. It separates depreciation from the lease finance charge, then applies the entered taxes, cash due, credits, and fees. The result is a comparison estimate, not a dealer quote.
Translate the offer into calculation inputs
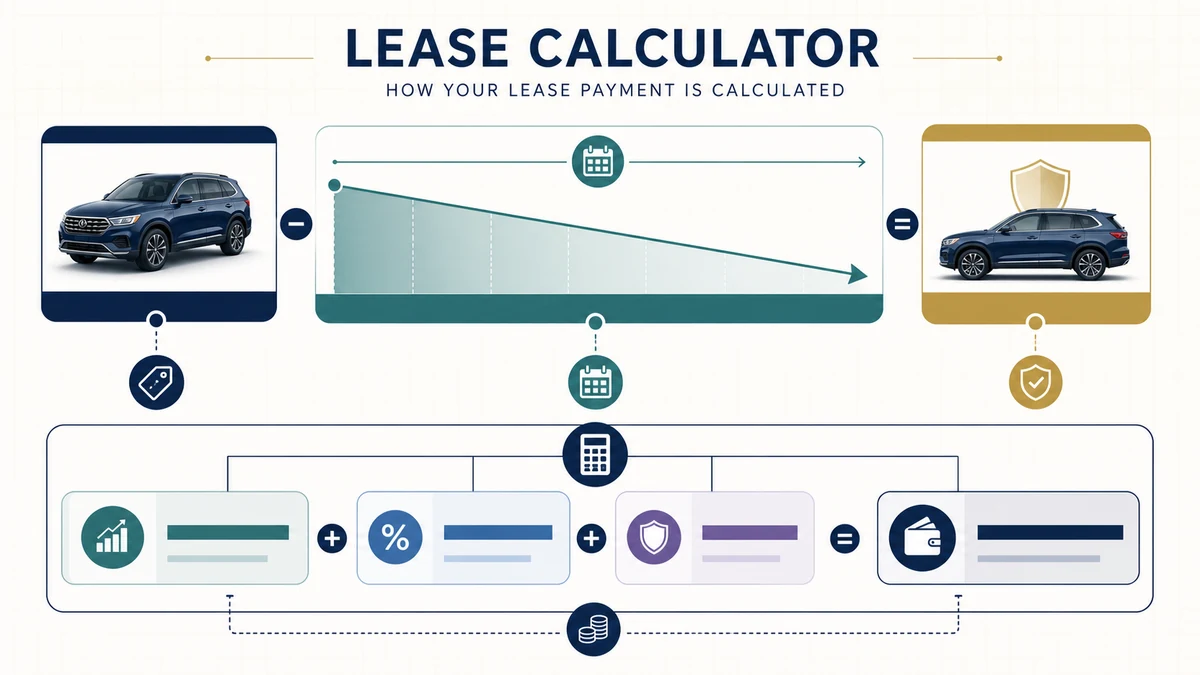
Collect the negotiated vehicle price, residual percentage or value, lease term, money factor or supported interest-rate input, acquisition and other fees, incentives, trade credit, down payment, tax method, and any amount due at signing. MSRP and negotiated price are not interchangeable.
Capitalized cost is the financed starting point
Adjusted capitalized cost generally starts with the negotiated price, adds capitalized fees, and subtracts capitalized reductions such as eligible incentives or cash. Confirm how the actual contract treats each item.
Depreciation and finance charge build the base payment
Monthly depreciation = (adjusted capitalized cost − residual value) ÷ lease months
A common money-factor model uses:
Monthly finance charge = (adjusted capitalized cost + residual value) × money factor
Add the two components, then apply taxes as required by the selected method. Contracts and jurisdictions can differ.
A simplified lease payment example
For adjusted capitalized cost of $36,000, a $24,000 residual, 36 months, and a 0.00200 money factor, depreciation is $333.33 monthly and the finance charge is $120. The base payment is about $453.33 before applicable tax and noncapitalized charges.
Compare total outlay, not only the ad payment
Add monthly payments, cash paid upfront, acquisition and disposition fees, and likely mileage or wear charges. Subtract only refundable deposits or credits where appropriate. A large down payment can make the advertised monthly payment look smaller without reducing the full risk proportionally.
Mileage and end-of-lease terms are part of the price
The FTC explains that a lease purchases the right to use a vehicle for agreed time and miles. Check mileage allowance, excess-mile charge, wear standards, maintenance, insurance, early termination, purchase option, and disposition charge.
Why visibility collapsed—and what this page now answers
Earlier GSC impressions clustered around “lease payment calculator,” “auto lease calculator,” “monthly lease payment calculator,” and related cost-estimator queries. This rewrite makes the payment components, total cost, and quote-checking intent explicit while keeping the Lease Calculator central.
Compare the obligation safely
Check affordability with the Budget Calculator, compare a purchase loan with the Personal Loan Calculator, and include the new payment in the DTI Calculator.
Lease Calculator FAQ
Is money factor the same as APR?
No. They are different expressions; use the conversion disclosed by the lessor and calculator.
Does a higher residual lower the payment?
Under the simplified model, it reduces modeled depreciation, although contract pricing still controls.
Are taxes included?
Only when entered and modeled using the applicable method.
Consumer source
Federal Trade Commission: financing or leasing a car.
Cash due at signing needs itemization
The amount collected at signing can include the first payment, acquisition fee, registration, tax, security deposit, and a capitalized-cost reduction. Only some components reduce the financed cost, and a refundable deposit is different from a down payment. Ask for an itemized worksheet before entering one lump sum.
Check the money factor independently
A money factor can be converted to an approximate annual percentage by multiplying by 2,400, but the lease disclosure and calculator convention control the actual comparison. A dealer markup or credit tier may change the offered factor. The Lease Calculator should be run with the factor on the written quote.
End-of-term scenarios
Compare returning the vehicle, exercising a purchase option, or facing excess mileage and wear. The future market value is unknown, so do not assume positive “lease equity.” If an early exit is possible, read the termination formula; remaining payments alone may not equal the liability.