Student Loan Calculator
Estimate monthly student loan payments, total interest, total repayment cost, payoff time, and savings from extra monthly payments.
Student Loan Results
This calculator provides an estimate only. Actual student loan payments can differ because of repayment plan type, subsidized interest rules, income-driven repayment, deferment rules, capitalization, fees, refinancing, loan servicer policies, and payment timing.
The Student Loan Calculator estimates a standard fixed-payment loan from balance, annual rate, repayment term, and optional extra monthly payment. It can show scheduled payment, total interest, estimated payoff time, and potential savings—but federal and private loan programs can operate differently.
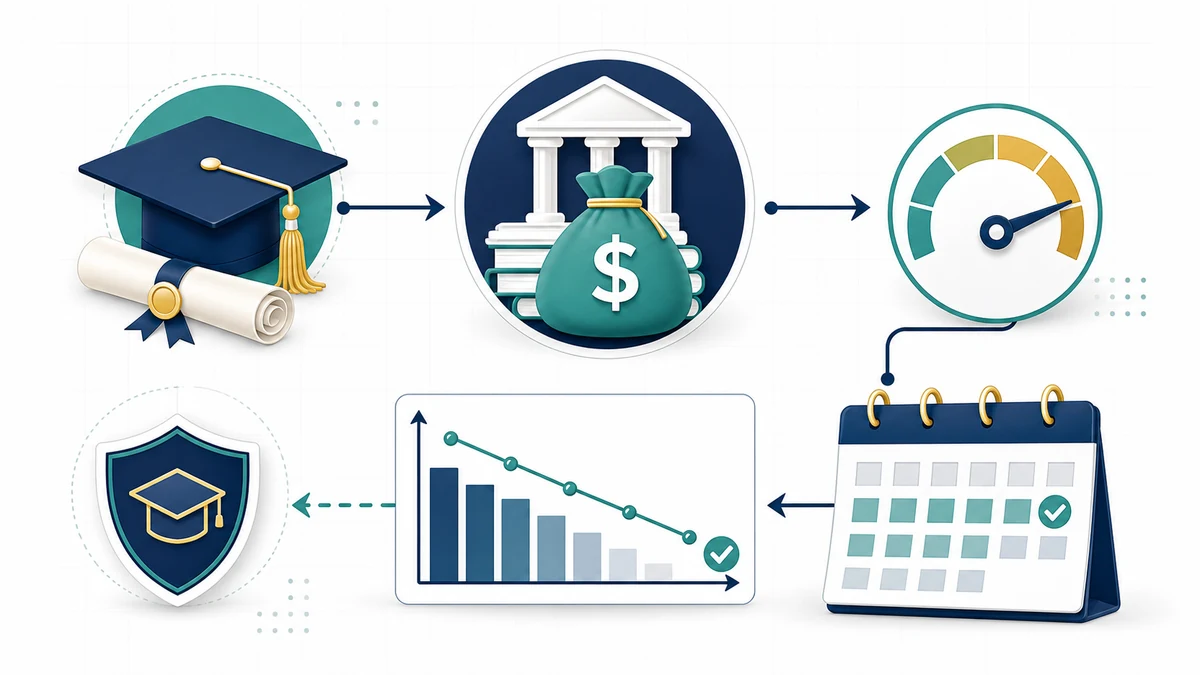
Understand which balance enters repayment
Use the current principal plus any interest that will capitalize before repayment when the calculator expects a starting balance. Capitalization can cause future interest to accrue on a larger principal. Confirm the figure with the loan servicer.
The fixed-payment model
Convert the annual rate to a monthly rate and use the standard amortization equation:
Payment = P × r × (1 + r)n ÷ [(1 + r)n − 1]
Here P is principal, r is the monthly rate, and n is the number of payments. A zero-interest loan is simply principal divided by months.
What extra payments may change
An extra payment directed to principal can reduce later interest and shorten payoff under a fixed-rate model. Confirm that the servicer applies extra funds as intended and does not merely advance the due date. Keep making required payments.
Why an official repayment plan may not match
Federal loans may offer standard, graduated, extended, or income-driven plans, and some borrowers may pursue consolidation or forgiveness. Payments can depend on income, family size, loan type, certification, and current program rules. The Student Loan Calculator does not determine eligibility or forgiveness.
Compare four outputs—not only monthly payment
- Required monthly payment.
- Total principal and interest paid.
- Estimated payoff date.
- Cash-flow effect of any extra payment.
A longer term may lower the payment while increasing total interest. A result that is mathematically cheapest is not useful if the payment is unaffordable.
Use current official information
Federal Student Aid states that its Repayment Calculator estimates eligible plan payments and total amounts, but final terms are set after processing. Program rules can change, so verify live options through StudentAid.gov and the servicer before acting.
Coordinate the payment with the household plan
Test affordability in the Budget Calculator, include the required payment in the DTI Calculator, and compare multiple debts with the Debt Payoff Calculator.
Student Loan Calculator FAQ
Does the estimate include income-driven repayment?
No, unless the tool explicitly requests the required program inputs and applies current rules.
Can the calculator guarantee forgiveness?
No. Eligibility and qualifying payments require official review.
Why is servicer interest different?
Daily accrual, capitalization, timing, fees, and plan rules can differ from a simplified monthly model.
Official repayment tool
Federal Student Aid Repayment Calculator guidance.
Interest accrual does not always pause with payments
During some deferment or forbearance periods, interest can continue accruing and may later capitalize. A temporary zero payment can therefore increase total cost. Use the official federal tool or servicer information for a pause scenario instead of deleting months from a fixed-payment schedule.
Multiple loans may need separate rows
Loans with different rates do not behave like one balance at an average rate unless the weighting and terms are correct. Model them individually, then add required payments. The Student Loan Calculator can be used for each fixed loan while the federal Repayment Calculator handles program-specific options.
Records to compare
- principal and accrued interest;
- fixed or variable rate;
- repayment-plan name and payment;
- estimated total paid and payoff date;
- autopay reduction and eligibility conditions;
- qualifying-payment or forgiveness records where applicable.
Never refinance federal loans without understanding which federal protections and options could be lost.
Before making an extra payment, keep a statement showing the balance and interest, then verify the next statement. This provides evidence that the payment was allocated as expected and lets the Student Loan Calculator restart from an accurate updated balance.