Loan Comparison Calculator
Compare two loan offers by monthly payment, total interest, fees, total repayment, and overall estimated cost.
Loan A
Loan B
Loan Comparison Results
This calculator provides an estimate only. Actual loan costs may differ because of APR rules, compounding, lender fees, payment timing, prepayment rules, insurance, taxes, late fees, and whether fees are paid upfront or financed.
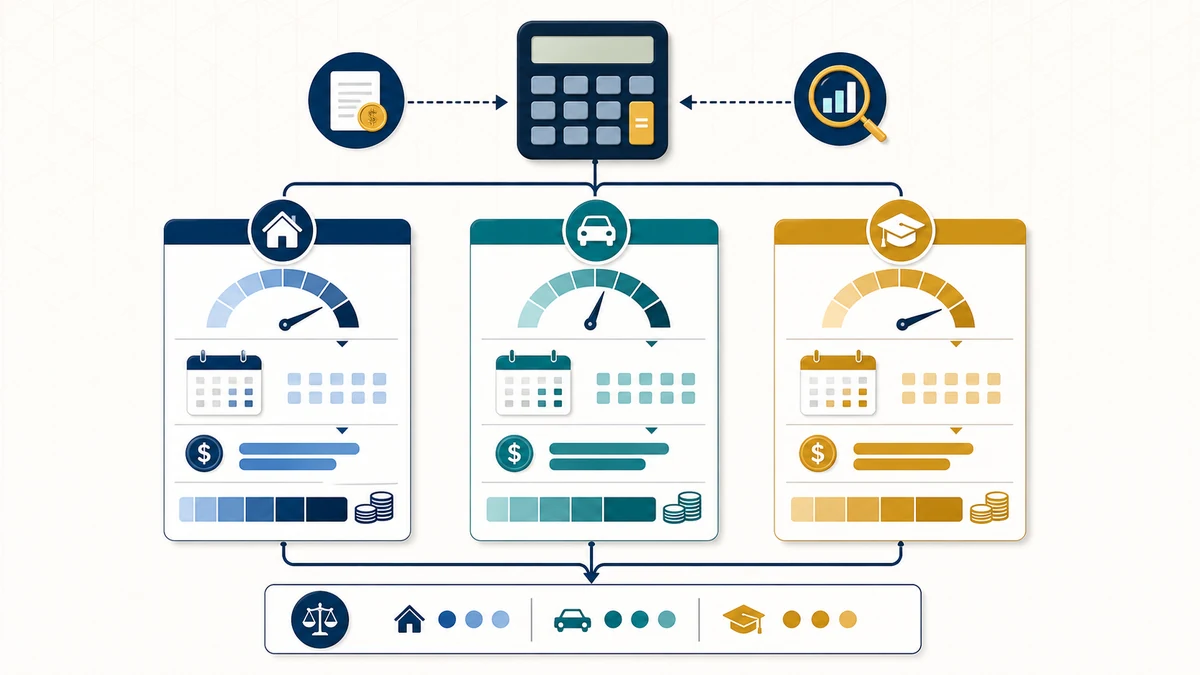
A Loan Comparison Calculator places two fixed-payment offers on the same basis. Enter principal, rate, term, and applicable fees for each. Then compare monthly payment, interest, total paid, and effective cash received rather than choosing the smallest advertised payment.
Normalize the offers before comparing
Make sure both offers fund the same need. If one lender deducts an origination fee, compare the net proceeds available to you—not only the face value. Convert terms to the same time unit and distinguish an interest rate from APR.
Why the lower payment can cost more
Extending the term spreads principal across more payments. That can ease monthly cash flow while increasing the months in which interest accrues. A five-year offer may therefore have a lower payment and a higher total cost than a three-year offer.
Read the comparison in this order
- Net proceeds money actually available after deducted fees.
- Required payment: the recurring cash-flow obligation.
- Total interest: modeled finance cost from the rate and schedule.
- Fees: origination and other included charges.
- Total paid: scheduled payments plus relevant upfront costs.
- APR: the disclosed annual cost measure used on a like-for-like basis.
A simple tradeoff example
Offer A and Offer B may both finance $15,000. A lower rate with a $900 origination fee can be more expensive for a short term than a slightly higher no-fee offer. The exact crossover depends on term, payment timing, and how fees are treated. Enter the disclosures rather than estimating from promotional language.
Questions the calculator cannot answer
The Loan Comparison Calculator cannot judge lender service, approval likelihood, collateral risk, variable-rate changes, late-fee behavior, hardship options, or whether borrowing is suitable. It also cannot replace legally required disclosures or the signed agreement.
Run at least one adverse scenario
Check whether each payment remains affordable if income falls or another essential expense rises. For variable offers, a fixed-rate model is insufficient. For extra-payment plans, verify prepayment and allocation terms with each lender.
Follow the comparison into the budget
Test the selected payment with the Budget Calculator, measure the new obligation with the DTI Calculator, or inspect one offer in detail with the Personal Loan Calculator.
Loan Comparison Calculator FAQ
Should I compare APR or interest rate?
Use APR against APR for a standardized cost comparison, while also reviewing actual fees and payment terms.
What if loan amounts differ?
Normalize the amount or compare net proceeds and total costs carefully; otherwise the result is not like for like.
Does total interest include every fee?
No. Keep interest and fees visible as separate components before reviewing total cost.
Consumer reference
CFPB explanation of interest rate and APR.
Use a comparison date
Rates and offers expire. Save the lender, date, face amount, net proceeds, APR, term, payment, fees, and total of payments shown in each disclosure. If one offer changes, update that side rather than comparing it with a stale quote.
Secured and unsecured loans carry different risks
A lower-cost secured loan may put property at risk after default. The Loan Comparison Calculator can compare dollars but cannot price the personal consequence of collateral, a co-signer, automatic-payment condition, or variable-rate exposure. Keep those terms beside the numeric result.
Decision checkpoint
- Is the amount borrowed and cash received equivalent?
- Are both rates fixed for the full term?
- Are mandatory products or discounts included?
- Does either offer have a balloon payment?
- Can the monthly payment withstand a budget shock?
- Are early payoff and late-payment terms understood?
Choose only after the comparison reflects the contract, not just the headline rate.
If an offer bundles insurance or another optional product, calculate with and without it. Reopen the Loan Comparison Calculator whenever a lender revises the disclosure so the decision is based on final, simultaneous terms.