Compound Interest Calculator
Calculate final balance, total contributions, and interest earned with optional recurring deposits.
Inputs
Recurring Deposits
Results
Use this Compound Interest Calculator to estimate how an initial balance and optional recurring deposits may grow over time through compounding. It calculates final balance, total contributions, interest earned, and effective annual rate.
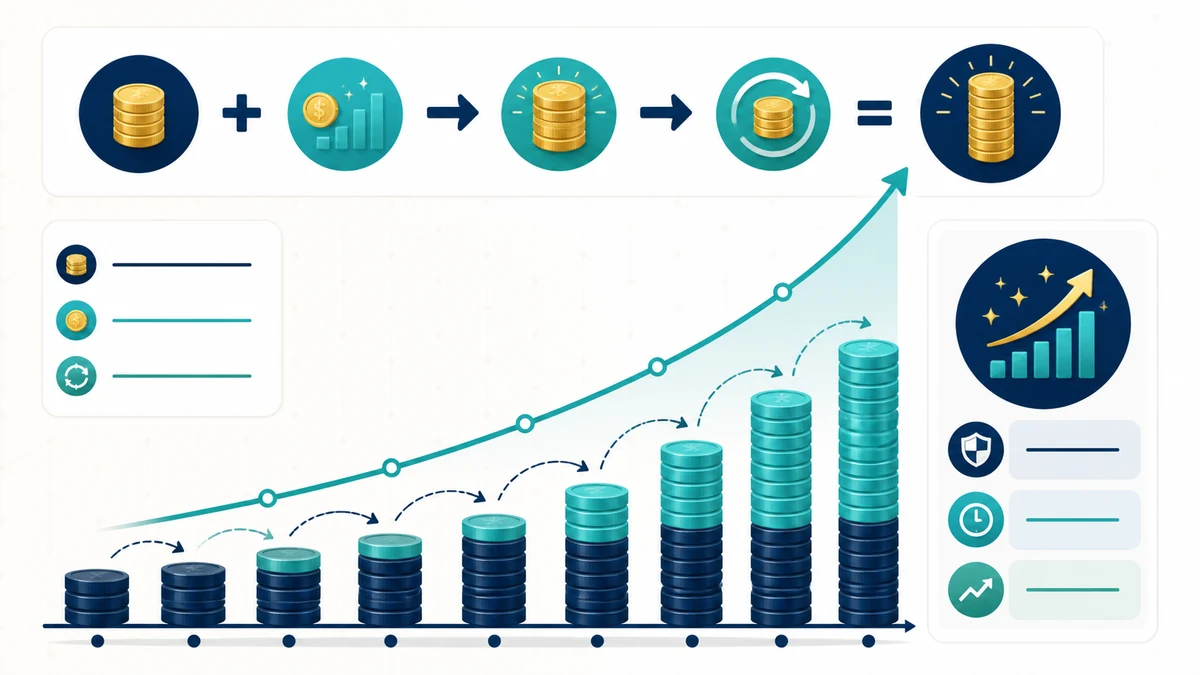
Important: The calculator assumes a fixed interest rate and regular deposits. Actual savings or investment results can differ because rates, returns, fees, taxes, and contributions may change over time.
Compound Interest Formula
Without recurring deposits, compound growth is calculated as:
Final balance = P × (1 + r ÷ n)n × t
Where:
- P = initial balance
- r = annual interest rate as a decimal
- n = number of compounding periods per year
- t = time in years
The interest earned is:
Interest earned = final balance − total contributions
Total contributions include the initial balance plus any recurring deposits you add.
Effective Annual Rate
The calculator also shows the effective annual rate, which reflects the effect of compounding:
Effective annual rate = [(1 + r ÷ n)n − 1] × 100
For the same nominal annual rate, more frequent compounding generally produces a slightly higher effective annual rate.
Recurring Deposits
You can include fixed recurring deposits made yearly, monthly, biweekly, or weekly.
Each deposit begins earning compound growth after it is added. Deposits made at the beginning of a period generally produce a slightly higher final balance than deposits made at the end of the period because the money has more time to grow.
Worked Example
Suppose you start with $5,000, earn an annual interest rate of 6%, compound monthly, and leave the money invested for 3 years with no additional deposits.
Final balance = $5,000 × (1 + 0.06 ÷ 12)36
Final balance ≈ $5,983.40
Interest earned:
$5,983.40 − $5,000 = $983.40
The effective annual rate is:
[(1 + 0.06 ÷ 12)12 − 1] × 100 ≈ 6.17%
Under these fixed assumptions, the original $5,000 grows by approximately $983.40 over three years.
Important Notes
- The calculator assumes the entered annual interest rate remains constant throughout the selected period.
- Recurring deposits are assumed to remain the same amount and occur consistently at the selected frequency.
- Beginning-of-period deposits have more time to compound than equivalent end-of-period deposits.
- Fees and expenses can reduce the amount available to earn interest or investment returns.
- Taxes, inflation, withdrawals, early-withdrawal penalties, changing rates, and account minimums are not included.
- For investments, an entered rate is only an assumed growth rate. Actual investment returns can fluctuate and may be negative.
- For savings products, compare the result with the financial institution’s stated interest rate, APY, compounding method, fees, and account terms.
How to Use the Compound Interest Calculator
Start with one clearly defined scenario and collect the values the calculator requests: principal, rate, time, compounding frequency, and recurring deposits. Use figures from current statements, quotes, pay records, contracts, or official documents whenever possible. Keep every rate and time period on the same basis before calculating. If one value is uncertain, enter a realistic estimate and then test a lower and higher alternative instead of treating a single forecast as certain.
Enter the values carefully, check the units, and calculate. The main results are future balance, total contributions, and compound growth. Save the assumptions alongside the result so you can reproduce the calculation later. For comparisons, change only one major input at a time. That makes it easier to see which variable is responsible for the difference and reduces the chance of comparing scenarios built on inconsistent assumptions.
How to Interpret the Results
This calculator is designed to show how earning returns on prior returns can accelerate growth over time. The result is an estimate based on the values supplied, not a quote, approval, tax ruling, investment recommendation, or contractual promise. Read the output together with its assumptions and compare the total cost or benefit—not only the most attractive headline number. A result that looks better in the short term may be less suitable when fees, timing, risk, or long-term obligations are included.
For a useful sensitivity check, recalculate with a less favorable rate, a different term, a larger cost, or a smaller income or return. Note the point at which the decision changes. This break point often provides more practical insight than a single best-case result because it shows how much uncertainty the plan can absorb.
Scenario Checklist
Before acting, confirm the source and date of every input; distinguish percentages from decimal values; include relevant fees and recurring costs; align monthly and annual figures; and verify whether values are before or after tax. Also consider inflation, opportunity cost, liquidity, and risk where relevant. Document the scenario name and calculation date so later comparisons use the same basis.
Important limitation: rates may change and fees, taxes, withdrawals, contribution timing, and risk can reduce actual results. Rules, market conditions, provider terms, and personal circumstances can change. Verify material decisions with the appropriate lender, employer, tax authority, regulator, financial professional, or contract documentation.
Related Finance Calculators
Continue your comparison with the CAGR (Compound Annual Growth Rate) Calculator and Dividend Calculator. Using related calculators can reveal costs or assumptions that a single result does not capture.
Frequently Asked Questions
What does the Compound Interest Calculator calculate?
It uses principal, rate, time, compounding frequency, and recurring deposits to estimate future balance, total contributions, and compound growth. The exact fields and displayed results depend on the values entered and the calculator formula.
Which inputs have the biggest effect on the result?
The inputs with the greatest effect are usually the largest balances, prices, rates, time periods, payments, or recurring amounts. Change one of these at a time and compare the results to identify the most sensitive variable.
How accurate is the Compound Interest Calculator?
It is mathematically accurate for the supplied inputs and stated assumptions. Real-world accuracy depends on the quality of those inputs and whether all relevant fees, taxes, timing rules, rate changes, and personal circumstances are represented.
How should I compare different scenarios?
Create a realistic base case, then a conservative case and an optimistic case. Keep units and timing consistent, alter one important assumption at a time, and compare total outcomes as well as periodic amounts.
Does the calculator include every tax, fee, and rule?
No general calculator can capture every jurisdiction, provider term, exemption, fee, or future change. Include additional costs where fields allow and confirm the final figures with current official documents or the relevant provider.
Can I use this result for an official financial decision?
Use it for education, planning, and initial comparison. Before signing, filing, investing, borrowing, or making another material commitment, confirm the assumptions and final numbers with authoritative documents and an appropriately qualified professional.
Sources
- Investor.gov — Compound Interest Calculator
- Investor.gov — What Is Compound Interest?
- Investor.gov — How Fees and Expenses Affect Investment Returns
Separate Contribution Growth From Interest Growth
When regular deposits are included, the final balance reflects both new money and returns earned over time. Confirm whether contributions occur at the beginning or end of each period, match the rate to the compounding frequency, and account for fees, taxes, or a variable rate when relevant. Compare scenarios using the same timeline so the effect of compounding is not confused with larger contributions.