Credit Card Interest Calculator
Estimate monthly interest using APR and average daily balance, plus projections.
| # | Balance start | Purchases | Interest | Payment | Balance end |
|---|---|---|---|---|---|
| Run a calculation to see the schedule. | |||||
A credit card interest calculator estimates how APR, balance and payment behavior affect borrowing cost. Enter figures from the latest statement or cardholder agreement, then compare payment scenarios instead of treating one forecast as a guaranteed bill.
How the Credit Card Interest Calculator Uses Daily Balances
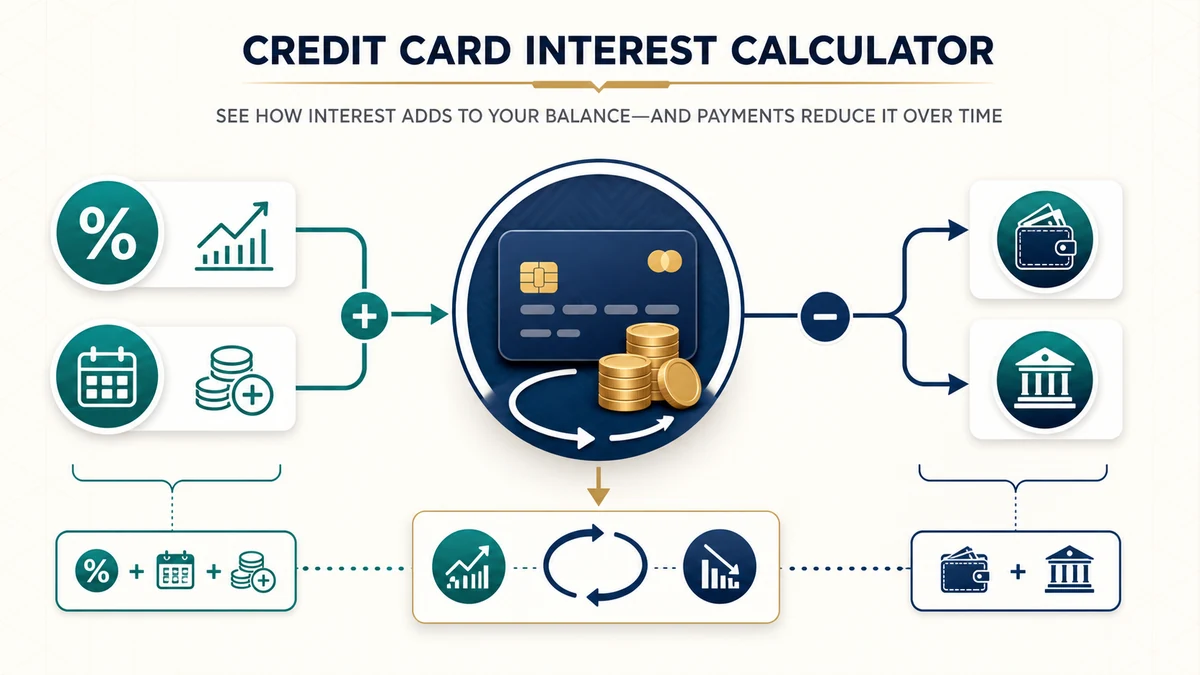
Credit-card rates are usually stated as an annual percentage rate. Many issuers calculate interest daily using a daily periodic rate related to APR, while statement methods and rounding can differ. Your agreement controls the actual charge.
Credit Card Interest Calculator Starting Balance
Use the balance to which the selected APR applies. Purchases, cash advances and transfers may sit in separate rate buckets. A single blended entry can hide the higher cost of one category.
Payment timing changes the result
Interest often depends on daily balances, so an earlier payment may reduce cost more than the same payment made later. Model the date and frequency options the tool supports, and do not assume every month contains the same number of days.
Minimum payment versus fixed payment
A minimum that declines with the balance can extend repayment. A fixed payment generally shortens payoff if no new charges are added. Test an affordable higher amount and compare total interest, not only the next statement’s payment.
Grace periods and carried balances
Purchase grace periods depend on account terms and whether the previous statement balance was paid in full. Once interest begins, residual or trailing interest may appear after a payoff payment. Check the issuer’s payoff figure before closing an account.
Scenario checklist
- Enter the correct APR for the balance type.
- Include annual or transaction fees separately.
- Set new purchases to zero for a pure payoff plan.
- Compare at least two payment amounts.
- Verify the plan against future statements.
The Consumer Financial Protection Bureau explains that many card companies calculate interest daily. This calculator is educational and does not reproduce every issuer rule.
How average daily balance affects interest
Many issuers add each day’s balance and divide by the number of days in the billing cycle, then apply a periodic rate. That means two accounts with the same closing balance may incur different interest if purchases and payments happened on different dates. For a close estimate, use transaction timing or average daily balance when the calculator offers it. A simple balance-times-APR calculation is better treated as a planning approximation.
Separate balances with different APRs
A card can contain purchases, a promotional transfer and a cash advance at the same time. Each may have its own APR, fee and interest-start date. Model each bucket separately, then add the estimated costs. Payment-allocation rules may direct amounts above the minimum toward the highest-rate balance, but the card agreement and applicable law determine actual handling.
Test a payoff plan before relying on it
Run one scenario using the contractual minimum and another using a fixed payment that fits the budget. Then stress-test the plan with a slightly higher rate or one missed month. If the chosen payment is less than estimated interest and fees, the balance can grow rather than decline. Stop adding new purchases in the model unless ongoing spending is part of the intended scenario.
Read the result as a forecast
- Total interest is the modeled cost, not an issuer payoff quote.
- Payoff time assumes payments arrive as entered.
- Variable APRs can change after the calculation.
- Annual, late, transfer and cash-advance fees need separate entries.
- Rounding and billing-cycle length can shift the final payment.
Recalculate after each statement using the new balance and actual APR. If repayment is becoming unmanageable, contact the issuer promptly and consider a reputable nonprofit credit counselor. Avoid making a major financial decision from a single optimistic scenario.
Compare repayment with the Balance Transfer Calculator while keeping fees and promotional deadlines visible.
credit card interest calculator FAQs
Is APR simply divided by 12?
That is a monthly approximation. Actual daily-balance calculations can differ.
Why does my statement charge differ?
Transaction dates, average daily balance, fees, multiple APRs, compounding and rounding may all contribute.
Does a zero balance stop every future charge?
Not always; trailing interest may remain. Request an official payoff amount when precision matters.