Personal Loan Calculator
Estimate monthly personal loan payments, total interest, total repayment, loan cost, and savings from extra monthly payments.
Personal Loan Results
This calculator provides an estimate only. Actual personal loan costs can differ because of lender fees, APR rules, payment timing, prepayment rules, late fees, credit profile, insurance add-ons, and whether fees are deducted upfront or added to the balance.
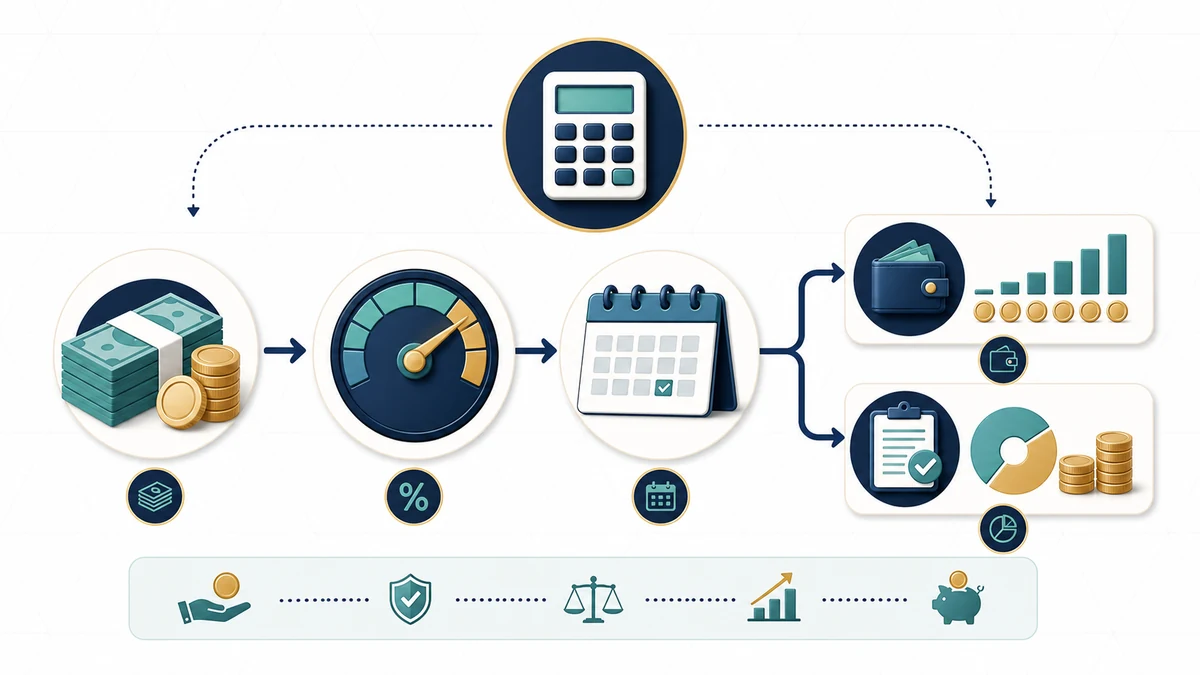
A Personal Loan Calculator converts principal, interest rate, and term into an estimated fixed monthly payment. Adding origination fees and optional extra payments reveals costs that a payment-only comparison can miss.
Principal received may differ from principal owed
Some lenders deduct an origination fee from loan proceeds while the borrower repays the full face amount. If a $10,000 loan carries a 5% fee deducted upfront, the borrower may receive $9,500 but still make payments based on $10,000. Enter the figures according to the calculator labels and loan disclosure.
Payment formula for an installment loan
Payment = P × r × (1 + r)n ÷ [(1 + r)n − 1]
P is principal, r is the monthly rate, and n is the number of payments. At zero interest, divide principal by payment count. The amortized payment covers interest first and reduces principal over time.
Interest rate and APR are not interchangeable
The interest rate prices borrowed principal. APR is designed to include the interest rate plus specified loan fees, expressed annually. The CFPB advises comparing APR with APR rather than comparing one lender’s rate with another lender’s APR.
A short-versus-long term tradeoff
A longer term typically lowers the scheduled payment but allows interest to accrue for more months. Use the Personal Loan Calculator to compare payment, total interest, fee, and total repaid under identical loan amounts—not just the monthly figure.
Test extra payments as a separate scenario
Extra principal may shorten payoff and reduce modeled interest. Check for prepayment terms and payment-allocation rules. Do not assume a lender will apply every extra dollar exactly as the simplified model does.
Before accepting an offer
- Verify net proceeds after fees.
- Compare APR, payment, total of payments, and term.
- Check late, returned-payment, and prepayment terms.
- Confirm whether the rate is fixed.
- Fit the required payment into a realistic budget.
Compare or prioritize the debt
Place two offers side by side with the Loan Comparison Calculator, include the payment in the DTI Calculator, or organize several balances with the Debt Payoff Calculator.
Personal Loan Calculator FAQ
Does APR determine the exact payment?
The contract’s interest rate, balance, term, and timing determine scheduled payments; APR supports cost comparison.
Are fees always deducted upfront?
No. The disclosure must show whether a fee is deducted, financed, or paid separately.
Will the estimate match the lender to the cent?
Payment dates, day-count methods, rounding, and fees can create differences.
Official cost definition
CFPB: interest rate versus APR.
Borrow only the amount the purpose requires
If an origination fee reduces proceeds, increasing the face amount to net the desired cash also increases scheduled interest. Calculate backward from needed proceeds and compare the full obligation. Avoid adding optional cash merely because a lender approves it.
Payment dates affect the first and last periods
A lender may use daily simple interest, a specific first-payment interval, or exact-day conventions. The Personal Loan Calculator uses a standardized schedule, so compare its total with the Truth in Lending disclosure and amortization schedule rather than expecting cent-for-cent identity.
Refinancing is a new cost decision
When replacing an existing loan, compare the old remaining interest and any payoff charge with the new fee, rate, term, and total cost. A lower payment created by restarting a longer term can increase the amount paid overall.
Protect personal information while comparing offers; calculations require amounts and rates, not account credentials, Social Security numbers, or application access.
Save the disclosure and the assumptions entered in the Personal Loan Calculator. If the approved amount, rate, fee, or first payment date changes, rerun the estimate before accepting the final terms.